A personal injury settlement is like a deal between you (the injured person) and the at-fault party, usually through their insurance company.
In the average personal injury settlement, injury victims agree to accept a specific amount of money in exchange for giving up the right to sue over the same incident in the future.
Put simply, a settlement means both sides have come to terms on how much compensation is fair.
The insurer pays your personal injury damages, and you agree that the matter is resolved.
While that might sound straightforward, reaching a settlement and actually getting the money in your hands are two separate parts of the process.
Settlements usually come after a process that includes claim evaluation, negotiation (within the legal process), and final agreement.
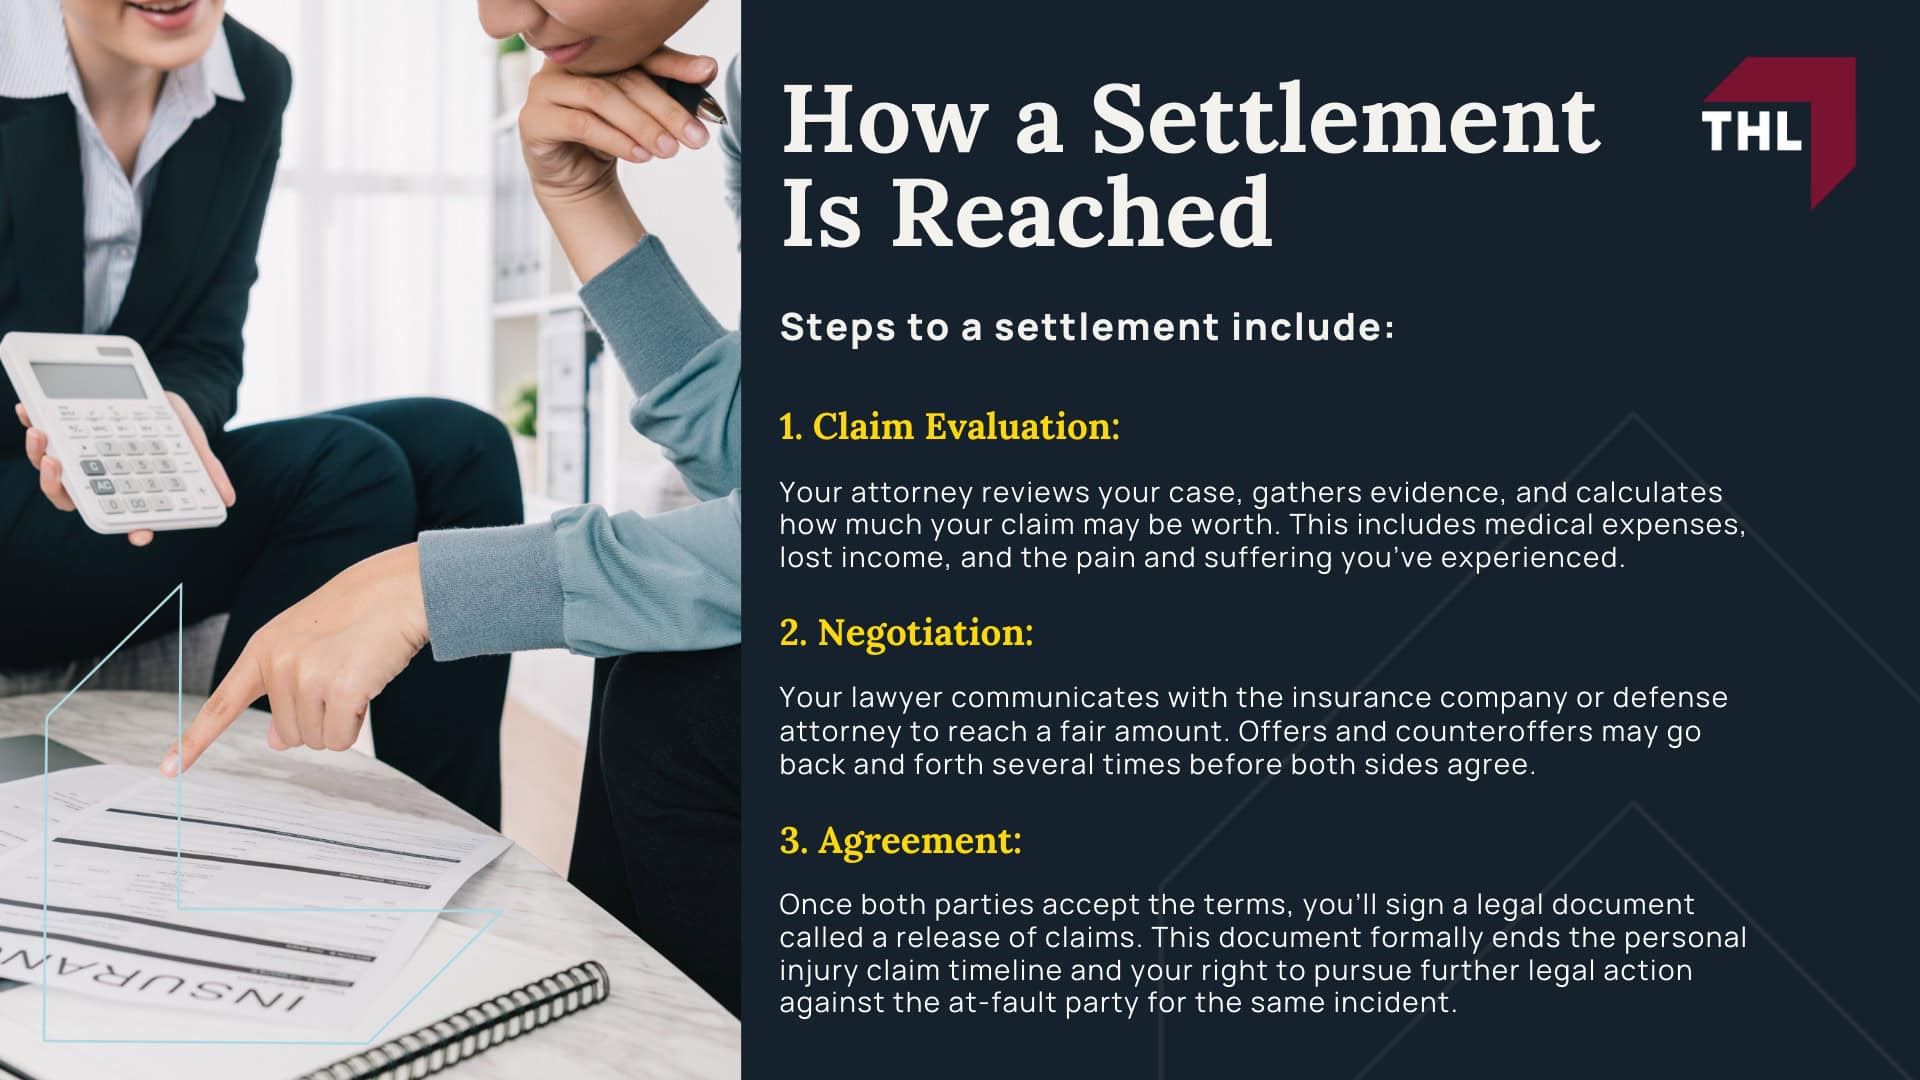
Steps to a settlement include:
After signing the release, your case is officially settled.
The money doesn’t arrive the same day.
The insurer still needs to process the payment, and your attorney must handle the necessary steps before you receive your portion.
Even after everyone signs, there’s still a short waiting period before you’re paid.
The insurance company must issue the settlement check, which is usually made payable to both you and your attorney’s law firm.
Your attorney then deposits it into a trust account.
It’s a special bank account that holds client funds until all case-related payments are handled.
Once all legal and administrative steps are complete, your lawyer deducts any agreed-upon legal fees and expenses, then releases the remaining funds to you.
Once a settlement is finalized, the next big question is how you’ll receive the money.
Personal injury settlements are typically paid in one of two ways: as a lump sum or as a structured settlement.
Each option works differently and has its own benefits depending on your financial goals and situation.
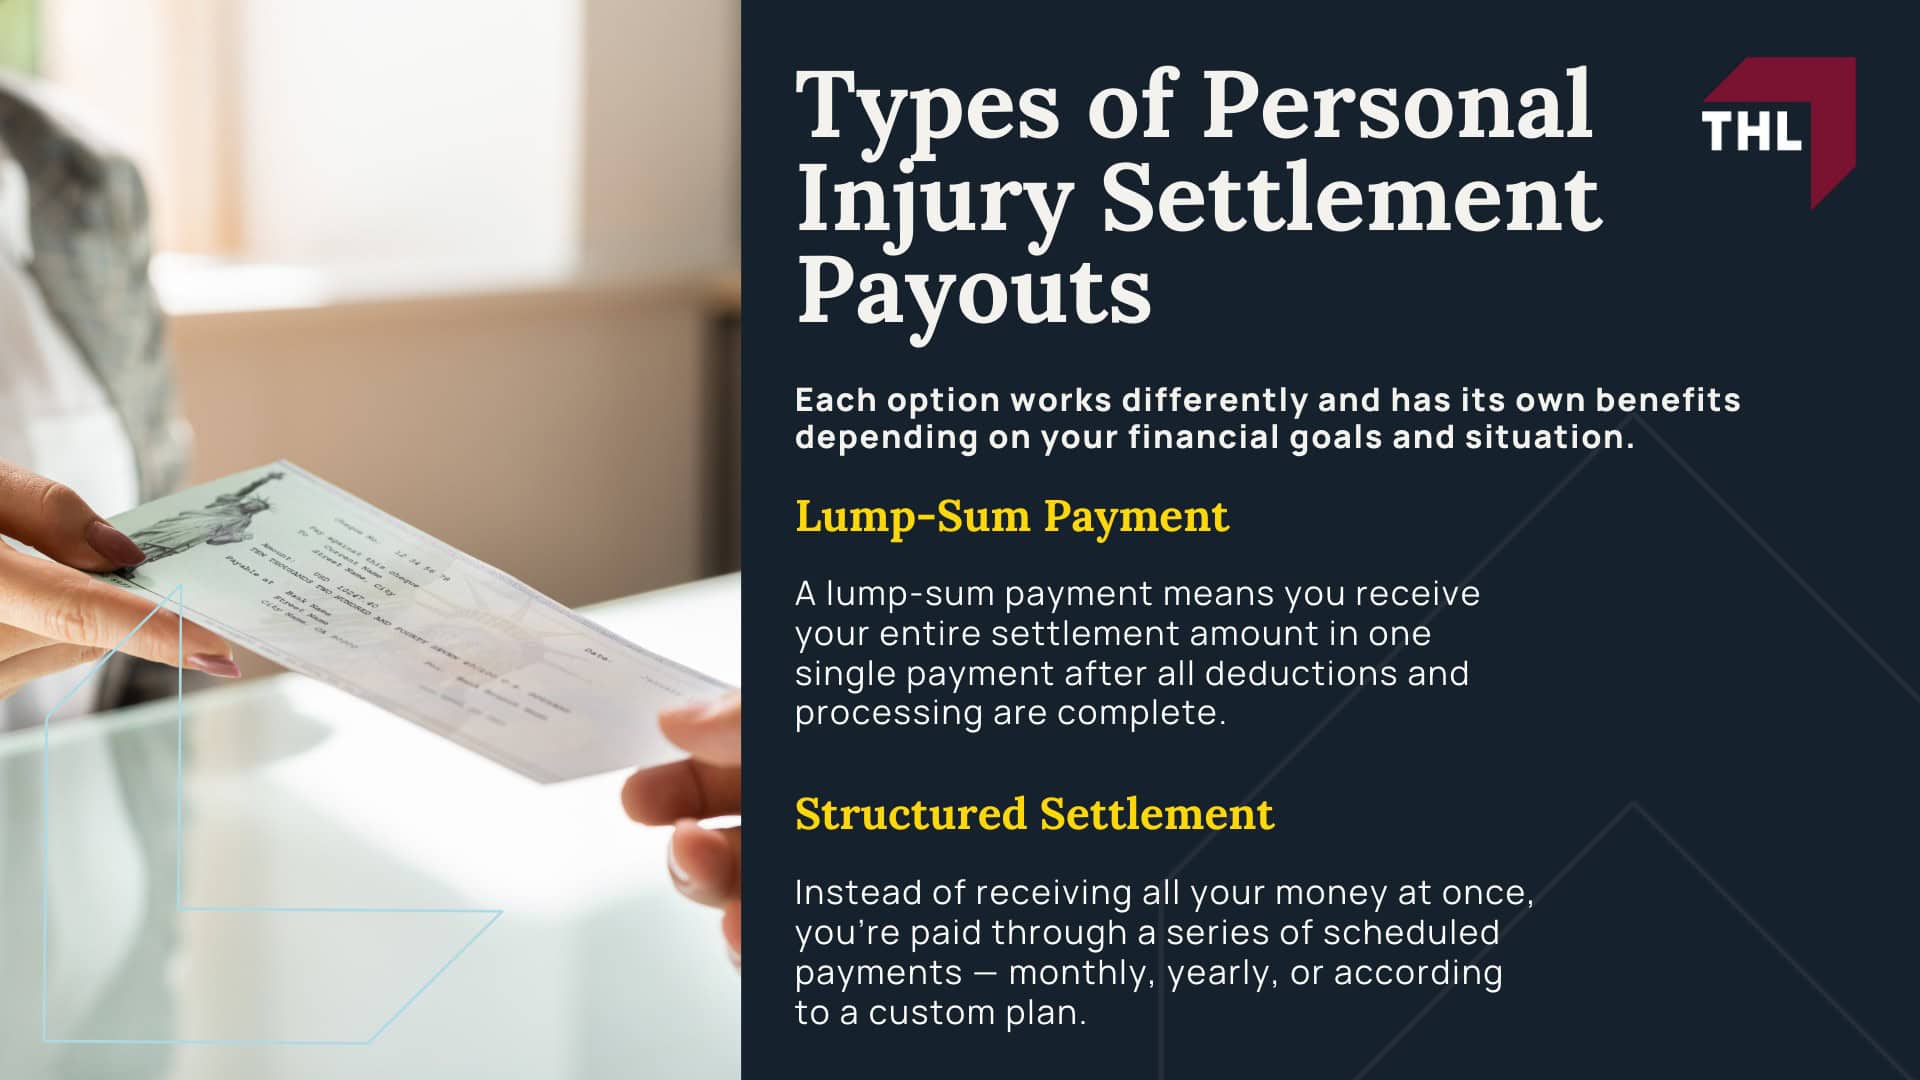
A lump-sum payment means you receive your entire settlement amount in one single payment after all deductions and processing are complete.
Most people prefer this option because it gives them quick access to their funds.
It also comes with responsibility.
Once you receive the payment, managing that money wisely is up to you.
There’s no second payout later if the funds run out.
This is why many lawyers recommend creating a budget or consulting a financial advisor before spending or investing the full amount.
A structured settlement works differently.
Instead of receiving all your money at once, you’re paid through a series of scheduled payments — monthly, yearly, or according to a custom plan.
Structured settlements are common in larger or long-term injury cases.
They can provide stability and peace of mind by guaranteeing future income, which can be helpful if you can’t return to work or expect ongoing medical costs.
Another advantage is potential tax benefits.
Under IRS rules, most structured settlement payments from personal injury cases are not considered taxable income.
This makes them an appealing choice for those seeking long-term financial security.
On the other hand, once a structured settlement is set, it’s generally fixed.
You can’t easily change the payment schedule later or request a lump sum.
That means you’ll need to plan carefully to ensure it aligns with your current and future financial needs.
There’s no universal answer for which payment structure is “best.”
A lump sum offers immediate control, while a structured settlement provides consistent support over time.
The right choice depends on your circumstances, such as whether you need immediate funds or ongoing assistance.
When you work with an experienced personal injury lawyer, they can walk you through the pros and cons of each option and help you choose the payout structure that fits your goals and financial comfort level.
Accepting a settlement is a big step, but it’s not the final one.
As with the actual personal injury lawsuit process, there are steps before you can actually access your money.
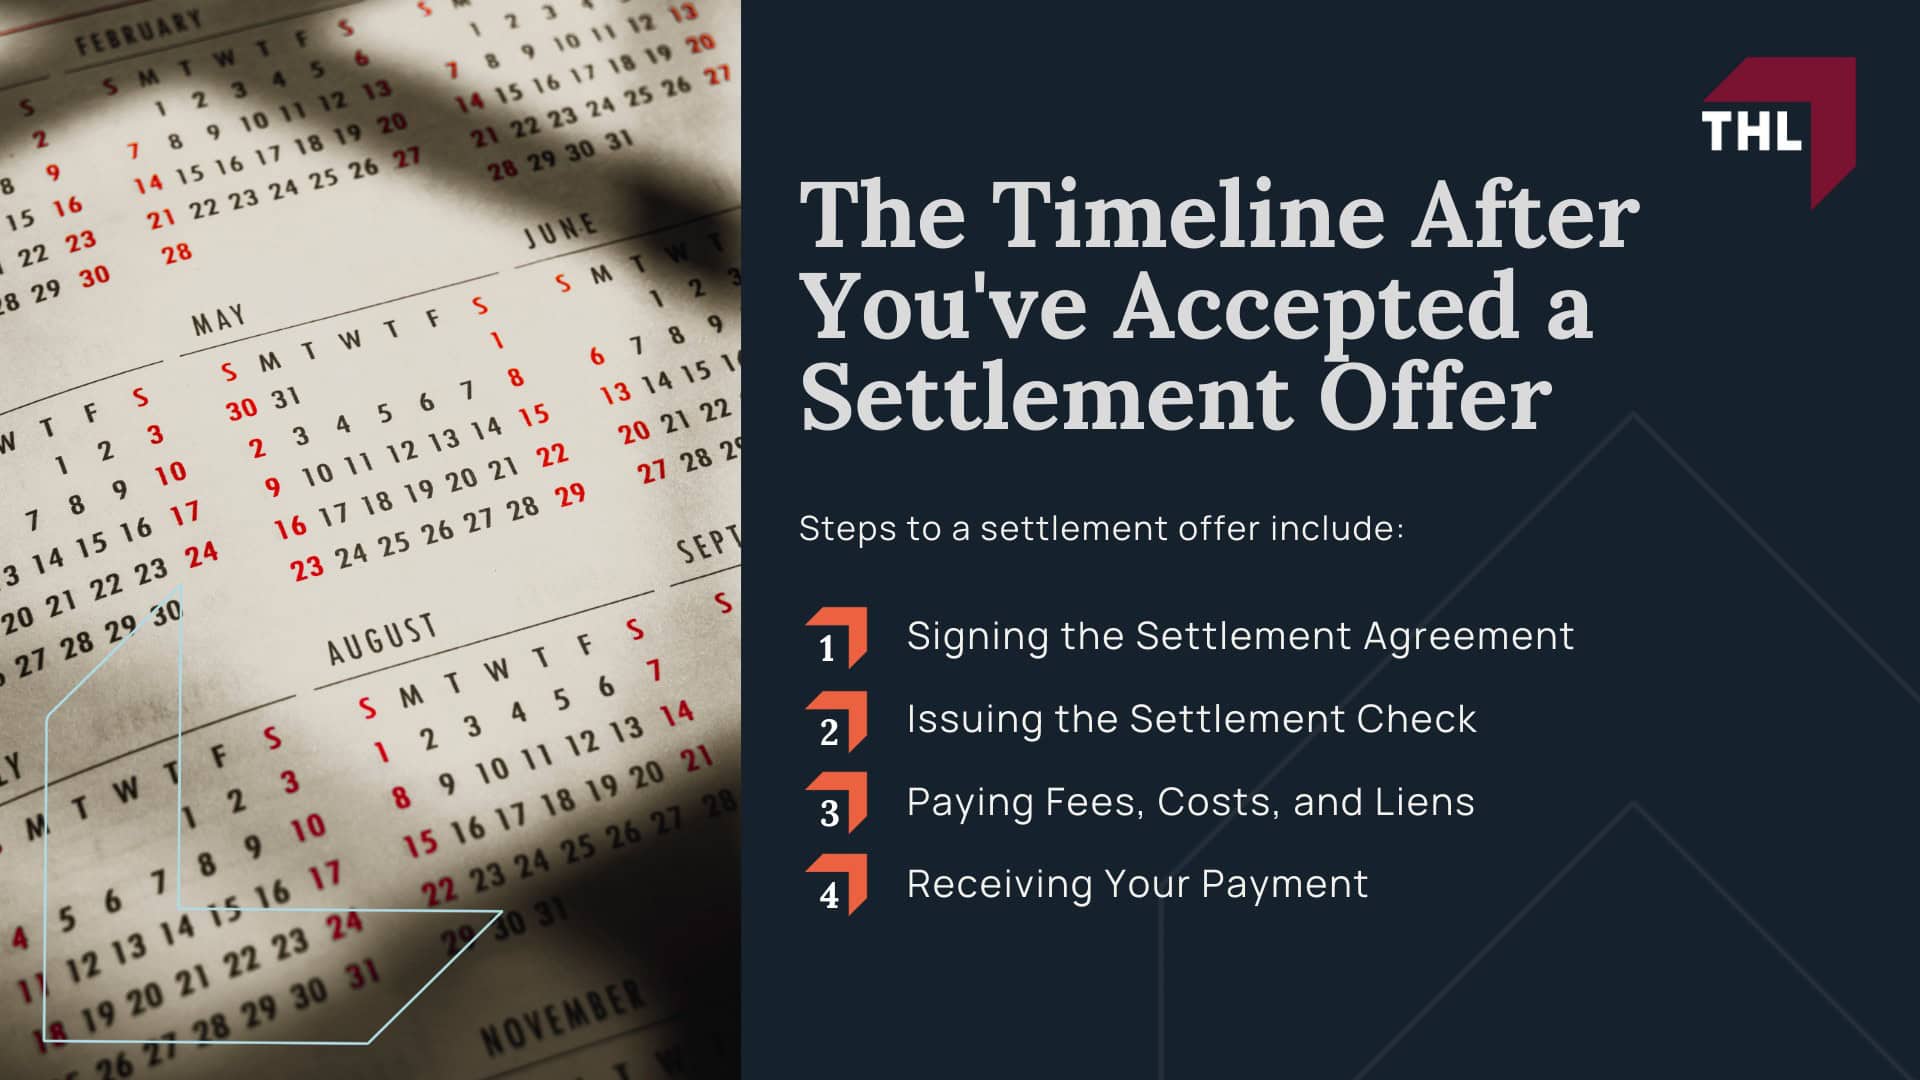
Steps to a settlement offer include:
Understanding the timeline can help you set realistic expectations and avoid unnecessary worry while waiting for your payment.
Once you and the insurance company agree on an amount, you’ll sign a settlement agreement or release of claims.
This legal document confirms that you accept the settlement and that you won’t pursue any more legal action against the at-fault party for the same injury.
Your attorney reviews this document carefully before you sign to ensure the terms are fair and accurate.
After it’s signed, your lawyer sends it back to the insurance company, so they can begin issuing payment.
After the paperwork is complete, the insurance company typically has a set period (often a few weeks) to send out the settlement check.
In many cases, the check is made payable to both you and your attorney’s law firm.
This practice ensures that funds are handled properly, and any outstanding costs are paid before the remaining balance goes to you.
The check is then deposited into your lawyer’s trust account — a secure bank account used to hold client funds until they’re ready for distribution.
This step can take several days, depending on the bank’s clearing process.
Before you receive your portion, your attorney will deduct any agreed-upon contingency fee (a percentage of the settlement you pay only if your case is successful).
They’ll also cover case expenses (like court filing fees, expert witness costs, and medical record requests) and resolve any medical liens.
A medical lien is a legal claim from a healthcare provider or insurer asking to be reimbursed from your settlement for the care they provided related to your injury.
Clearing these ensures you don’t face future bills or disputes once you’ve been paid.
Once all deductions are handled and funds have cleared, you’ll receive your payment — either in one lump sum or as part of your structured settlement plan.
In straightforward cases, this entire process usually takes four to eight weeks from the day the agreement is signed.
More complex cases, or those involving government entities or multiple lienholders, can take longer.
Your lawyer keeps track of each step and updates you on where things stand.
After the insurer releases your settlement payment, your lawyer manages the funds to make sure everything is handled correctly.
This process is designed to protect you from errors, missed payments, or future disputes about unpaid bills.
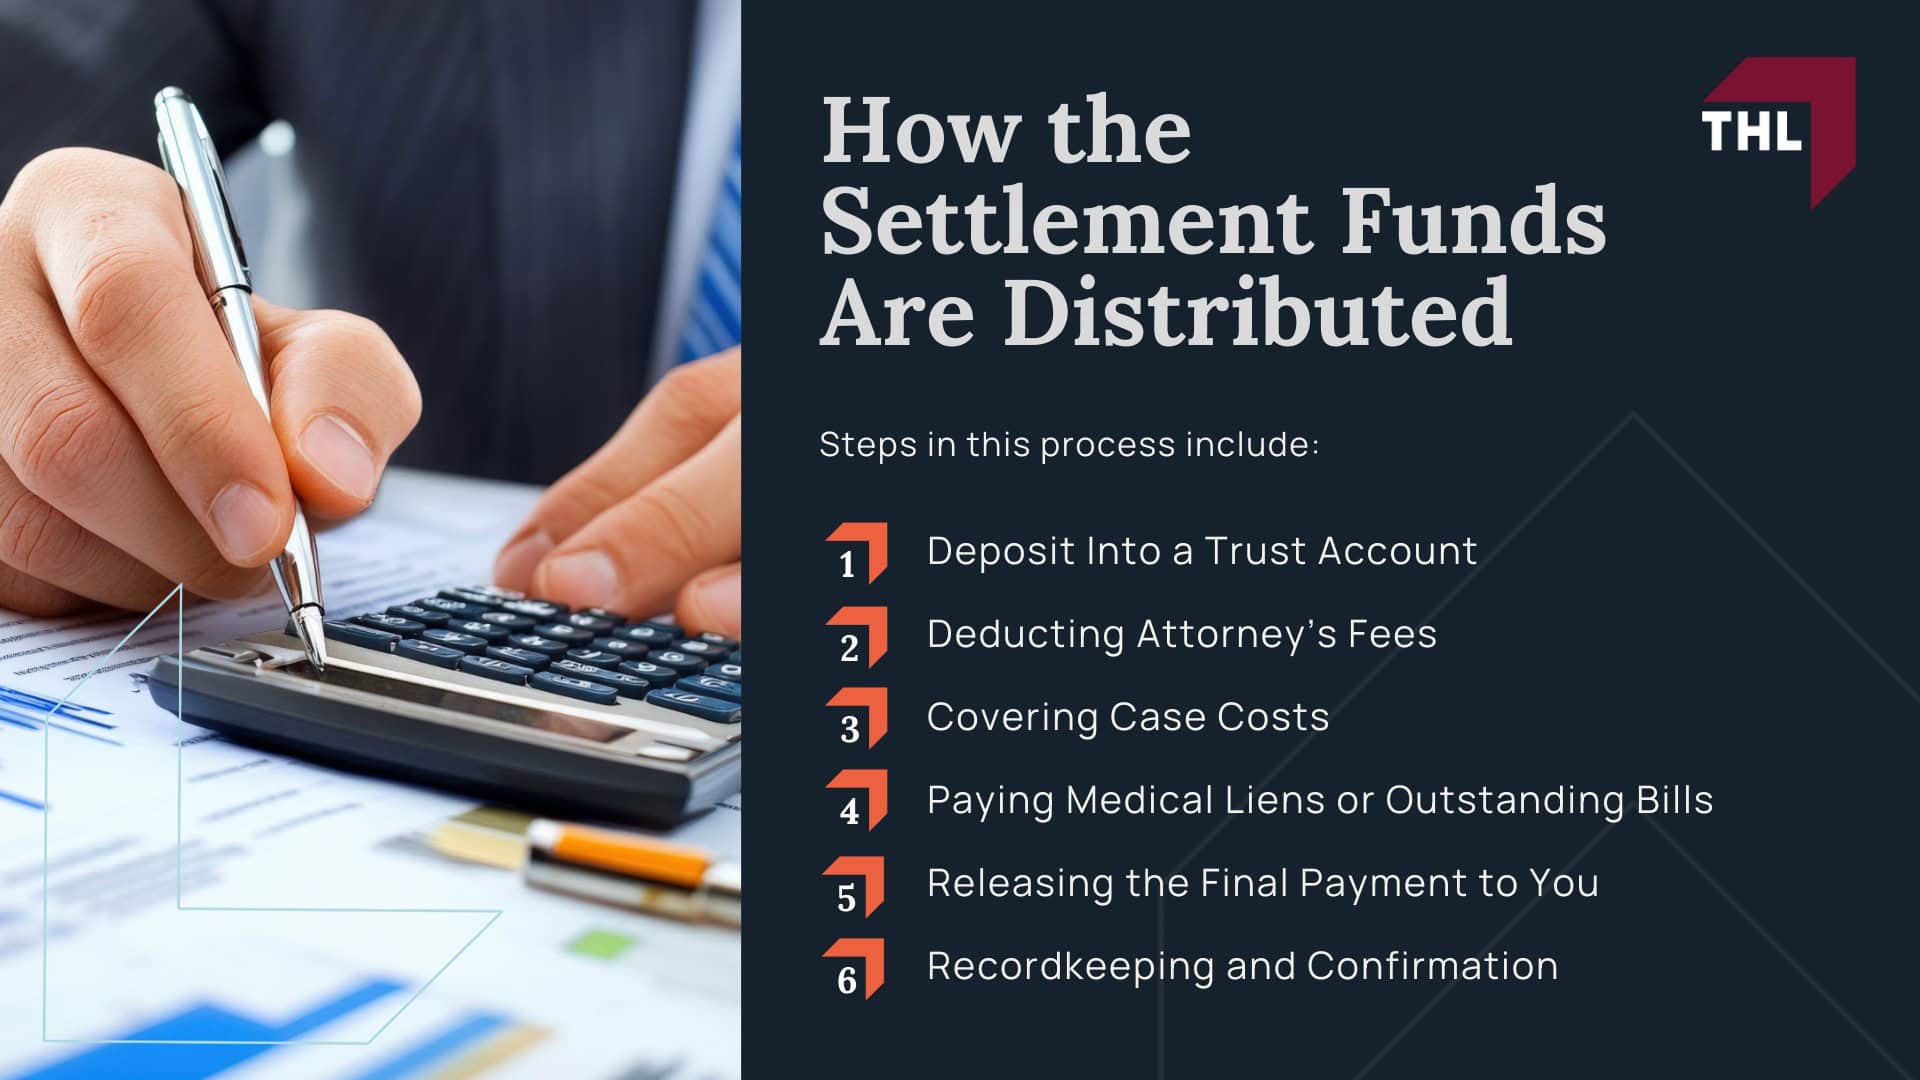
Steps in this process include:
The settlement check is first deposited into your attorney’s trust account.
This is a special bank account used only for client money.
The funds stay there until they fully clear, and your lawyer verifies the total amount.
No funds are released until the check clears — this can take several business days, depending on the bank.
Most personal injury cases work on a contingency fee basis, which means your lawyer’s payment depends on winning your case.
The typical fee ranges from 30% to 40% of the settlement, depending on the agreement you signed when hiring your attorney.
If your total settlement is $90,000 and your contingency fee is 33%, the attorney’s fee would be $29,700.
In addition to attorney’s fees, there are case expenses that were paid out during your case.
These can include filing fees, costs of medical record requests, payments to expert witnesses, and investigation expenses.
Your lawyer keeps detailed records of these costs and provides a full breakdown before final distribution.
If your case costs a total of $2,000, that amount would be deducted next.
If doctors, hospitals, or your health insurer placed liens on your case, your attorney will pay those directly from the settlement.
This step ensures those debts are cleared properly, so you won’t receive surprise bills later.
Say you have $15,000 in medical liens.
After paying the attorney fee and case costs, your lawyer would use part of the remaining balance to pay those liens in full.
After all deductions are complete, your attorney issues the remaining funds to you.
The resulting amount will be your net settlement.
Using our example:
Your lawyer may send this amount by check, direct deposit, or wire transfer, depending on your preference and their policies.
Finally, your lawyer will provide a detailed accounting sheet showing exactly how every dollar of your settlement was distributed.
This record is important for your own files and for tax purposes if any portion of your settlement (like punitive damages or certain interest payments) is taxable.
Even after you’ve filed your claim and a settlement is approved, several factors can affect how quickly and smoothly you receive your payment.
Some delays are routine, while others depend on the complexity of your case or the insurance company’s process.
Insurance companies issue settlement payments by check or electronic transfer.
Paper checks are more common, especially in personal injury cases, because they allow both the insurer and your lawyer to verify every step before funds are released.
Once the check is received, your attorney must deposit it into a trust account and wait for it to clear.
Most banks require several business days for this.
If your lawyer offers electronic disbursement, such as a wire transfer or direct deposit, your payment can arrive sooner once funds are cleared.
Each insurance company has its own internal process for approving and releasing payments.
While most issue checks within two to four weeks after receiving the signed settlement agreement, delays can occur if paperwork is incomplete, signatures are missing, or the case involves multiple parties.
Some insurers also require a final confirmation from their legal department or claims adjuster before sending the payment. Your attorney keeps track of these details and follows up to ensure nothing falls through the cracks.
In certain cases, a court must approve the settlement before payment is made.
This step is common if the injured person is a minor or someone under legal guardianship.
The court reviews the settlement to make sure it’s fair and protects the person’s best interests.
Once the judge approves the settlement, payment can move forward.
This extra step adds time — often a few additional weeks — before the funds are released.
If you’re still receiving medical care for your injury, or if there are unresolved medical liens, payment may be delayed until those bills are finalized.
Your attorney must ensure that every healthcare provider or insurer with a lien is properly reimbursed before you’re paid.
In some cases, your lawyer might negotiate with medical providers to lower their lien amounts.
While this takes time, it can increase your final payout.
If you choose a structured settlement, setting up the payment schedule requires coordination between your lawyer, the insurer, and a third-party annuity provider.
This process ensures your future payments are legally protected and funded properly.
Because these agreements are legally binding and customized to your needs, structured settlements often take longer to begin than lump-sum payments.
Once the structure is established, payments usually follow the agreed schedule with minimal delay.
When it’s time to decide how you want to receive your compensation, think practically about your needs now and later.
Each option has its strengths — it’s about matching the payout to your situation, not chasing the bigger number.
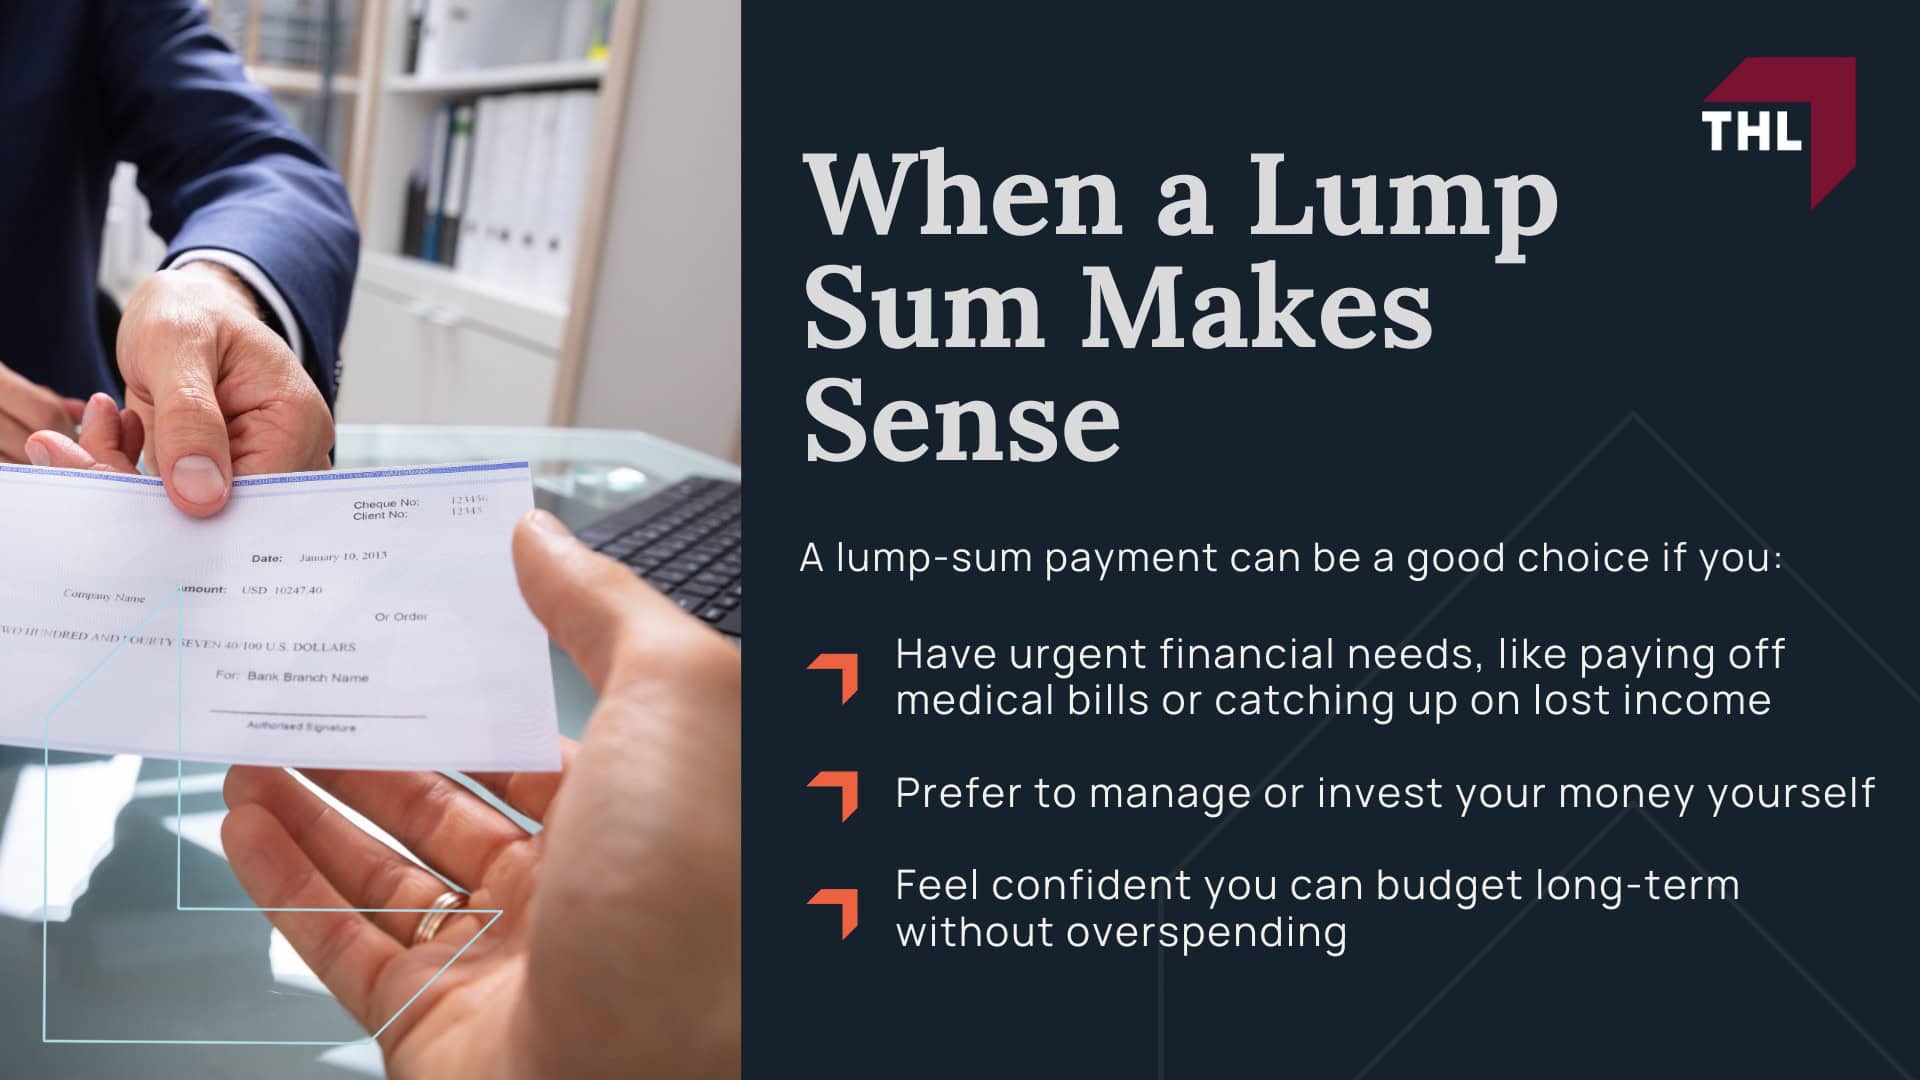
A lump-sum payment can be a good choice if you:
You get full access to your funds upfront, which means flexibility, but also full responsibility.
If you’re considering this route, talk to a financial advisor about how to protect and grow your payout responsibly.
When long-term medical needs and financial stability are priorities, a structured settlement can provide predictable, often tax-advantaged income instead of a single lump sum.
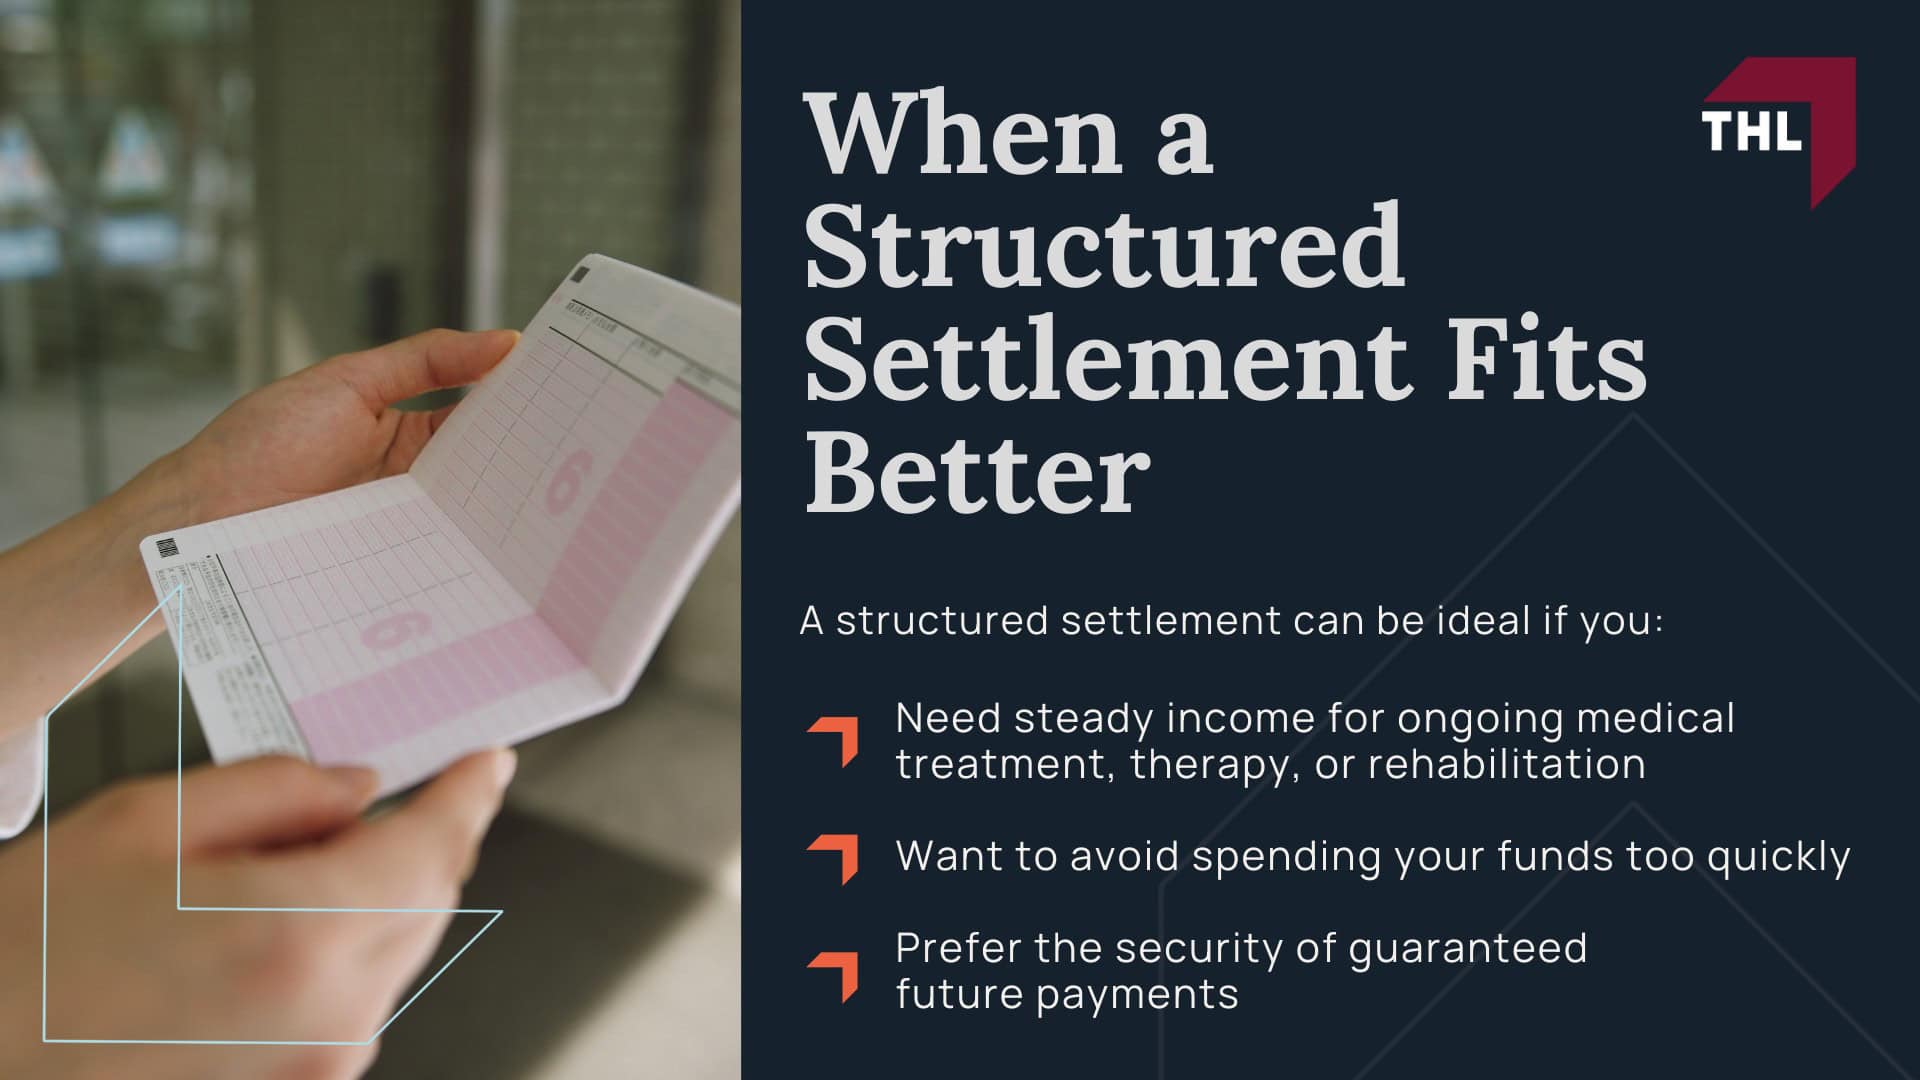
A structured settlement can be ideal if you:
Payments are arranged through an annuity, giving you a dependable source of income over time.
This structure can also reduce tax risks since most personal injury settlements are not considered taxable income under IRS rules.
Reaching a personal injury settlement is an important milestone, but understanding how that settlement is paid out helps you take control of your recovery and finances.
Whether your compensation comes as a lump sum or structured payments, the goal is the same: to make sure your losses are covered and your future is secure.
Working with an experienced personal injury lawyer makes this process simpler and more reliable.
At TorHoerman Law, we make sure every step, from the release of claims to the final disbursement, is handled properly and on time.
You’ll know exactly where your money is going, what deductions apply, and when you can expect to receive it.
You won’t have to pay anything upfront once we take your case.
We’re a call away if you’re pursuing a personal injury case. For a law firm that looks out for your best interests, contact TorHoerman Law and get a free consultation.
You can also use the chatbot on this page to find out if you’re eligible to file a claim.